Retirement Planning — Our Specialty
Retirement Planning
We specialize exclusively in helping pre-retirees and retirees build income plans that last a lifetime — with the analysis to prove it.
Why Retirement Planning Is Different
Accumulation is one skill. Distribution is another.
Growing a portfolio during your working years requires a certain discipline. But turning that portfolio into reliable, tax-efficient income for 20 or 30 years of retirement is an entirely different challenge — one that most generalist advisors are not built for.
Retirement income planning is our primary specialty at Platinum Wealth Management. That focus means deeper expertise, more refined strategies, and a process built specifically around the questions that matter most in retirement.
Our Process
How We Build Your Retirement Plan
Retirement Assessment
We begin with a comprehensive review of your assets, income sources, expenses, and retirement timeline to establish a clear picture of where you stand today.
Income & Distribution Modeling
We run detailed projections across multiple scenarios — market conditions, spending levels, longevity — to stress-test your plan and identify gaps before they become problems.
Social Security & Tax Strategy
We optimize the timing of Social Security benefits and coordinate withdrawals across accounts to minimize lifetime tax liability and maximize spendable income.
Ongoing Plan Management
Retirement is not a set-it-and-forget-it event. We monitor your plan continuously and adjust as markets, tax laws, and your personal circumstances evolve.
Our Process in Action
A real look at what we do for clients
We use professional retirement planning software to model each client's exact situation — year by year, dollar by dollar. Here's what that analysis actually looks like.
We show clients exactly where they stand.
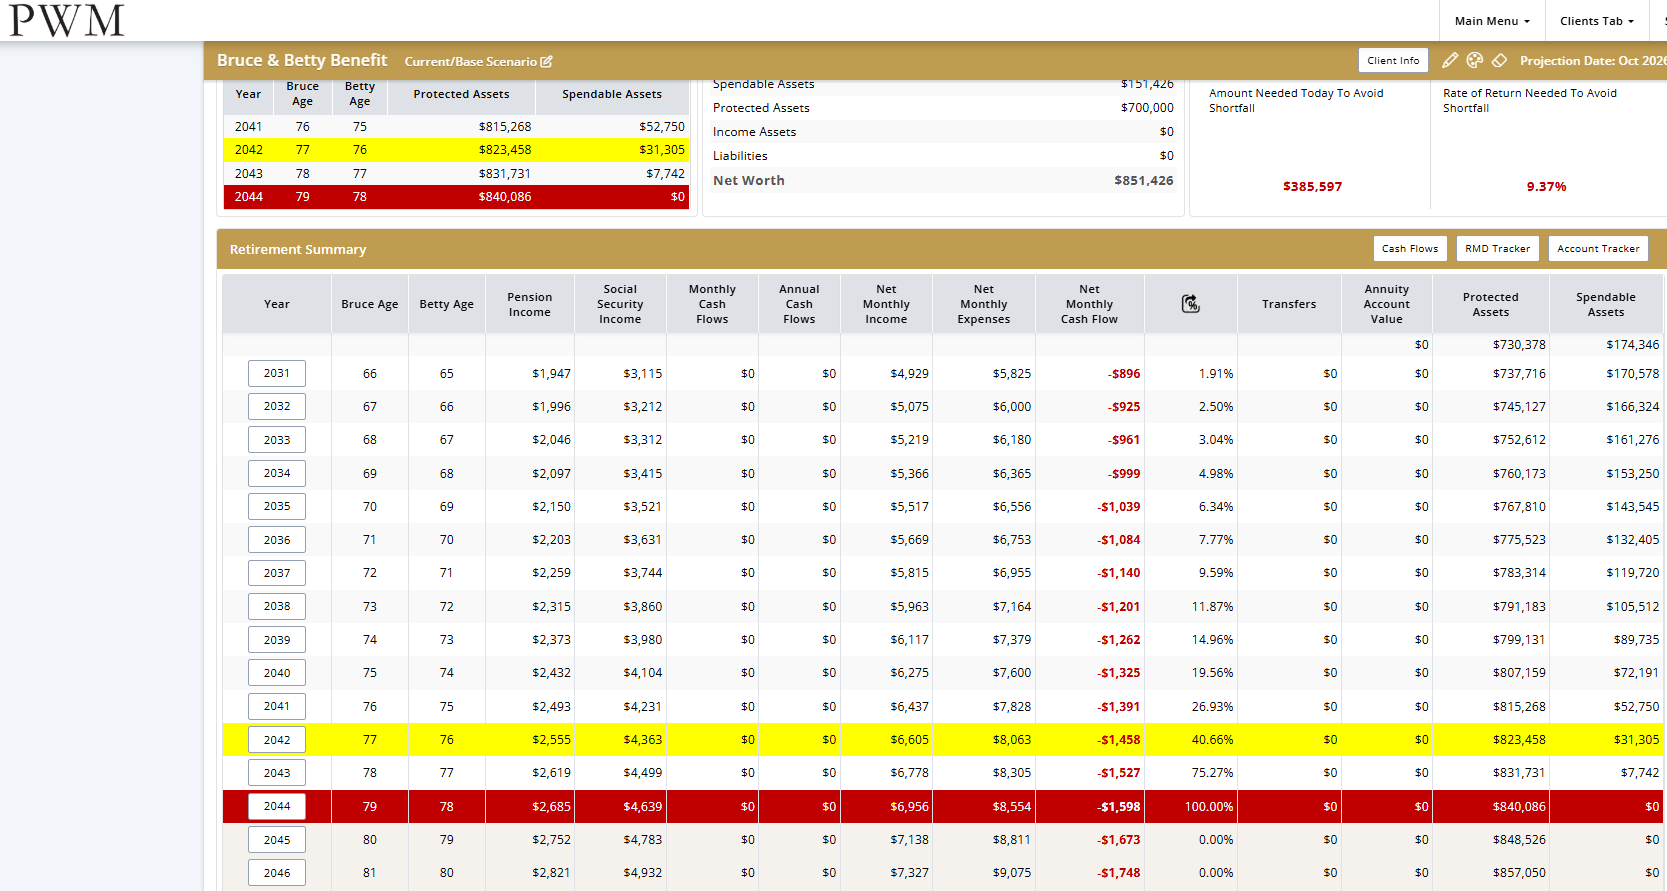
This couple runs out of money at age 78.
Using real numbers — pension income, Social Security, monthly expenses, and assets — we project year by year what the financial picture looks like. The red row is the depletion year: the exact point spendable assets hit $0. This is the problem we solve.
Then we fix it — and show the proof.
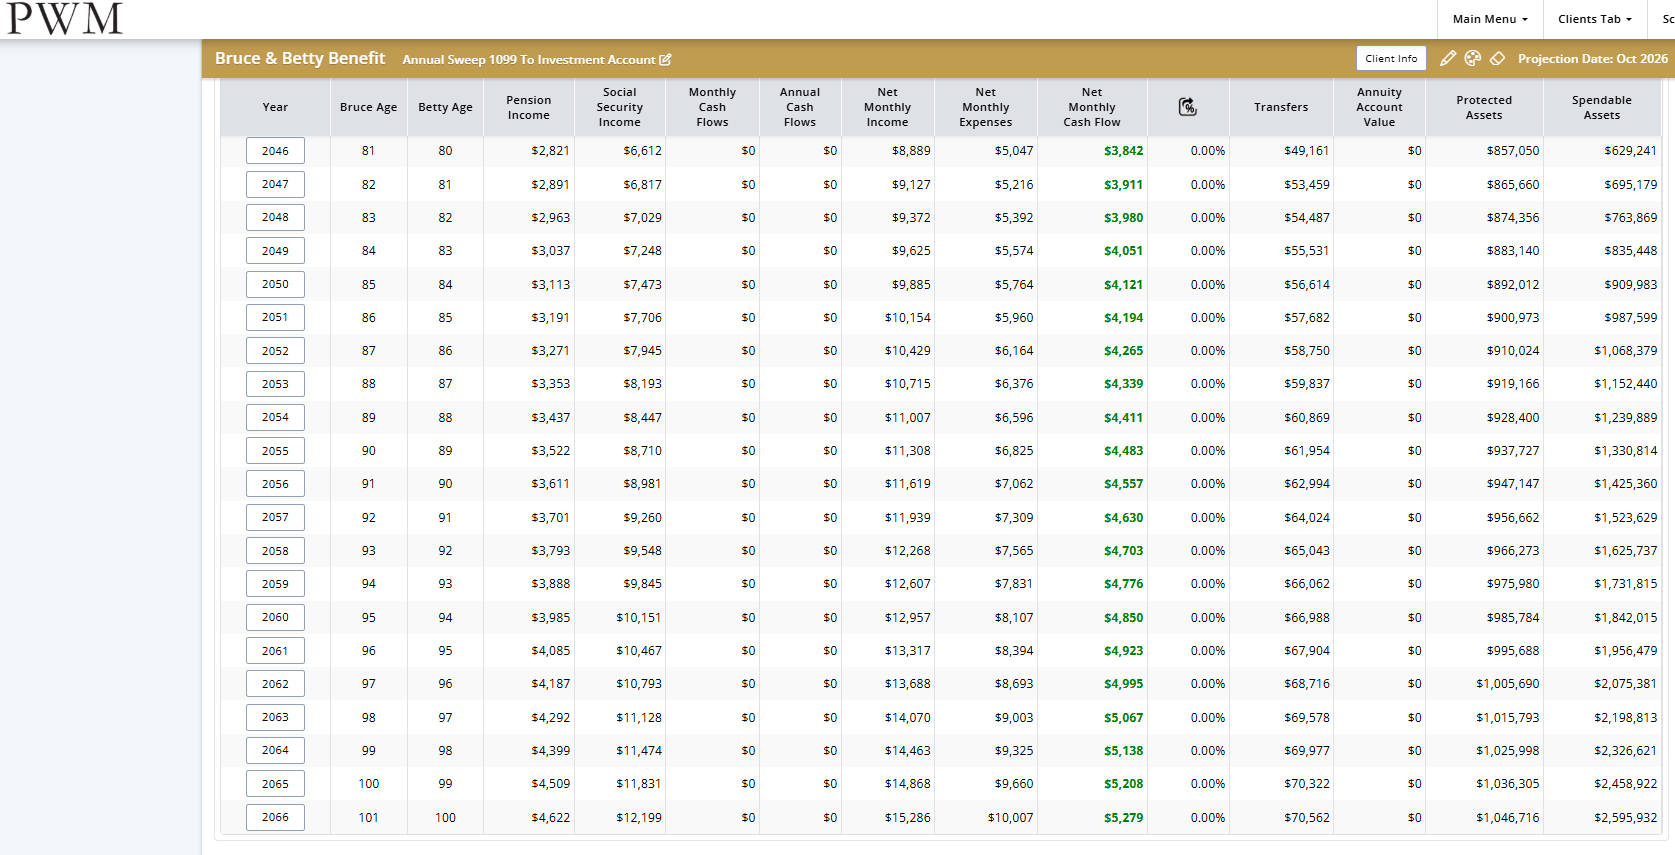
After identifying the problem, we apply our knowledge and strategies — repositioning assets for income, optimizing Social Security timing, coordinating RMDs, and reducing tax drag. The same couple who would have run out of money at age 78 now has $2,458,922 remaining at age 100. That is the difference a well-built retirement plan makes.
Same couple. Same income needs. $0 at age 78 → $2,458,922 at age 100.
Sample analysis shown for illustrative purposes. Client names are fictional. Actual results vary based on individual circumstances.
Is your retirement plan built to last?
Schedule a complimentary retirement assessment. No obligation — just clarity.